


Sending Money to Iran — Legal Guide
Sending money to Iran is possible under specific OFAC general licenses — primarily for personal remittances to family. Our lawyers explain exactly what is permitted, what is prohibited, and how to transfer funds to Iran in full legal compliance with OFAC regulations.
Message a sanctions lawyer on WhatsApp — confidential, reply within 24 hours.
Iran money transfer cases are among the most technically complex areas of OFAC practice. The difference between a legal remittance and an OFAC violation can come down to a single party’s SDN status, the routing bank used, or a missing document. Our OFAC licensing lawyers have handled Iran-related remittances, estate transfers, business wind-downs, and specific license applications across dozens of cases.
We can help you:
- Determine whether your transfer qualifies under an existing general license
- Conduct full SDN screening of all parties in the transaction chain
- Draft and submit an OFAC specific license application
- Respond to OFAC supplemental information requests
- Advise on compliant routing through third-country financial institutions
- Handle OFAC enforcement defense if a violation has already occurred
OFAC General Licenses for Iran: What Transactions Are Permitted
The U.S. Treasury’s Office of Foreign Assets Control (OFAC) maintains a set of general licenses under the Iranian Transactions and Sanctions Regulations (31 CFR Part 560) that authorize specific categories of money transfers to Iran without requiring individual license applications. Understanding which category your transaction falls into is the critical first step. The table below summarizes the currently active general license categories for Iran-related financial transfers as of 2025–2026.
| License Category | What’s Permitted | Key Conditions | License Type |
|---|---|---|---|
| Personal Remittances to Family | Sending money to close family members in Iran for personal/household expenses, living costs, medical care, and education | Non-commercial purpose only; no SDN-listed recipients; must route through non-U.S. financial institution; no fixed dollar cap | General License (automatic) — 31 CFR § 560.550 |
| Educational Fees & Student Support | Tuition payments, academic fees, books, and living expenses for Iranian students studying outside Iran; educational materials to Iran | Payments must be for personal academic use; no benefit to Iranian government or state institutions; no commercial resale | General License (automatic) — 31 CFR § 560.550 |
| Humanitarian Transfers | Food, medicine, medical devices, and personal medical expenses; donations to recognized NGOs operating in Iran | Items/funds must meet OFAC humanitarian definition; NGO must not be SDN-listed; no dual-use goods; separate GL covers donations to charities (GL 8A related) | General License (automatic) — ITSR Humanitarian Provisions |
| Family Support — Inherited & Estate Funds | Transfer of inherited cash or proceeds from sale of property acquired before U.S. immigration; closing inherited bank accounts in Iran | Property must have been acquired before sender’s U.S. immigration; no SDN-listed parties in transaction; court/estate documentation required | General License (conditional) — specific license may be required for complex estates |
| Monetary Gifts (Non-Commercial) | One-time monetary gifts to individuals in Iran for personal use (weddings, emergencies, personal support) | No commercial purpose; recipient must not be SDN-listed or connected to Iranian government; no business investment | General License (automatic) — 31 CFR § 560.550 |
| Blocked Funds / Iranian Financial Institutions | Certain transactions involving Iranian financial institutions blocked under Executive Order 13902 (Iran General License L) | Narrow scope; applies to specific authorized financial institutions only; legal counsel strongly advised | Iran General License L (issued Oct. 2020) |
| Post-Immigration Property Sales | Proceeds from selling property in Iran acquired after the sender immigrated to the U.S. | Specific OFAC license required — not covered by general license; application must document full transaction history | Specific License Required |
| Business & Commercial Payments | Not permitted under any general license; requires specific OFAC license (rarely granted) | Prohibited for virtually all U.S. persons and companies; specific license process can take 6+ months | Specific License Required (rarely approved) |
Important: Even transactions covered by a general license may be blocked if any party in the transfer chain — sender, recipient, intermediary bank, or exchange house — appears on OFAC’s Specially Designated Nationals (SDN) list. Always conduct full SDN screening before proceeding. Our OFAC licensing attorneys provide SDN screening as part of every consultation.
Message a sanctions lawyer on WhatsApp — confidential, reply within 24 hours.
Iran Money Transfer: Frequently Asked Questions
The following questions are among the most common we receive from individuals and families navigating Iran money transfer rules. Each answer reflects current OFAC regulations under 31 CFR Part 560 as of 2025–2026.
Can I send money to my family in Iran?
Yes — personal remittances to close family members in Iran are permitted under OFAC General License (31 CFR § 560.550) without requiring a separate application. You may send funds for living expenses, medical care, and education. The transfer must be non-commercial, must not benefit SDN-listed individuals, and must route through a third-country bank (not directly through U.S. financial institutions).
Which banks process Iran money transfers legally?
No major U.S. bank can directly process transfers to Iran — U.S. financial institutions are prohibited from serving as the direct conduit for Iran-side transactions. Legal transfers typically route through banks in Turkey, the UAE, Germany, or other countries that maintain correspondent banking relationships with Iranian banks not on the SDN list. Non-U.S. banks such as certain Turkish and UAE institutions may facilitate the Iran leg of the transfer, but you must verify their SDN status. Using an OFAC-experienced attorney to identify compliant routing is strongly recommended.
What is the maximum amount I can send to Iran?
There is no fixed dollar cap for personal remittances under the OFAC general license (31 CFR § 560.550). However, larger transfers attract greater scrutiny. The transfer must be for personal/household purposes — not investment, business, or commercial use. Transfers above certain thresholds may trigger Bank Secrecy Act (BSA) reporting requirements (e.g., Currency Transaction Reports for amounts over $10,000). For large remittances, we strongly advise obtaining a legal opinion confirming compliance before proceeding.
Can I send money to Iran for educational fees?
Yes — educational fees and student support payments fall within the personal remittances general license under 31 CFR § 560.550. This covers tuition payments, academic fees, books, and living expenses for Iranian students. The key condition is that the payment must be for personal academic use — not to Iranian state educational institutions (which may be SDN-linked). Payments to private universities or educational institutions outside Iran on behalf of Iranian students are generally permissible.
Is Western Union available for sending money to Iran?
No — Western Union, Wise, Remitly, and most major money transfer operators do not offer direct transfers to Iran from the U.S. These companies are U.S.-regulated entities and cannot process Iran-side transactions without an OFAC export service license (31 CFR § 560.418), which none currently hold for personal remittances. Transfers must instead route through authorized third-country exchange houses or correspondent banking channels. Be cautious of services claiming to offer Western Union or Wise-based Iran transfers — these are compliance red flags.
Do I need an OFAC license to send humanitarian aid to Iran?
Not always — many humanitarian transfers are covered under existing general licenses. Food, medicine, medical devices, and personal medical expenses are authorized under ITSR humanitarian provisions without a specific license application. However, charitable donations to organizations operating in Iran require a specific license, as does any transfer that benefits an Iranian government entity or SDN-listed organization. If you are sending funds through an NGO or charity, confirm their licensing status before transferring.
What happens if I accidentally send money illegally to Iran?
Even accidental or good-faith violations of Iran sanctions can result in civil penalties of up to $377,700 per violation (or twice the transaction value) (or twice the transaction value). OFAC does not require intent for civil violations. If you have already made a transfer that may violate sanctions, the most important immediate step is voluntary self-disclosure — which typically results in significantly reduced penalties. Contact an OFAC attorney immediately to assess your exposure and prepare a disclosure if needed.
Wire Transfers to Iran: What Is Permitted vs. Prohibited
| Transfer Type | Status | Conditions |
|---|---|---|
| Family remittances (personal) | Permitted (general license) | To non-SDN family members; personal use only |
| Humanitarian payments (food, medicine) | Permitted (general license) | Not to Iranian government; authorized recipients only |
| Legal services fees | Permitted (general license) | Payment for legal representation in U.S. proceedings |
| Dollar-denominated commercial transfers | Prohibited | Blocked by U.S. correspondent banks |
| Transfers to Iranian government entities | Prohibited | Includes Central Bank of Iran |
| Transfers to SDN-listed individuals/entities | Prohibited | Full asset block applies |
| OFAC-licensed specific transactions | Permitted with licence | Requires prior OFAC specific licence application |
Conducting business in a global economy often has risk and requires flexibility and the ability to quickly adapt to changing conditions. However, when it comes to financial transactions involving Iran, caution is paramount. The Iran sanctions regime established by the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) leaves no room for error. Any deviation from established norms can lead to severe consequences, including asset freezes and criminal prosecution. The detailed regulations set forth in sanctions programs 31 CFR Part 560 (Iranian Transactions and Sanctions Regulations, ITSR) are the key aspect of conducting any transactions involving Iran. If you are planning to wire transfer from Iran to the United States or other countries or vice versa, this process will require not only knowledge but also legal support at every stage of underlying transaction.
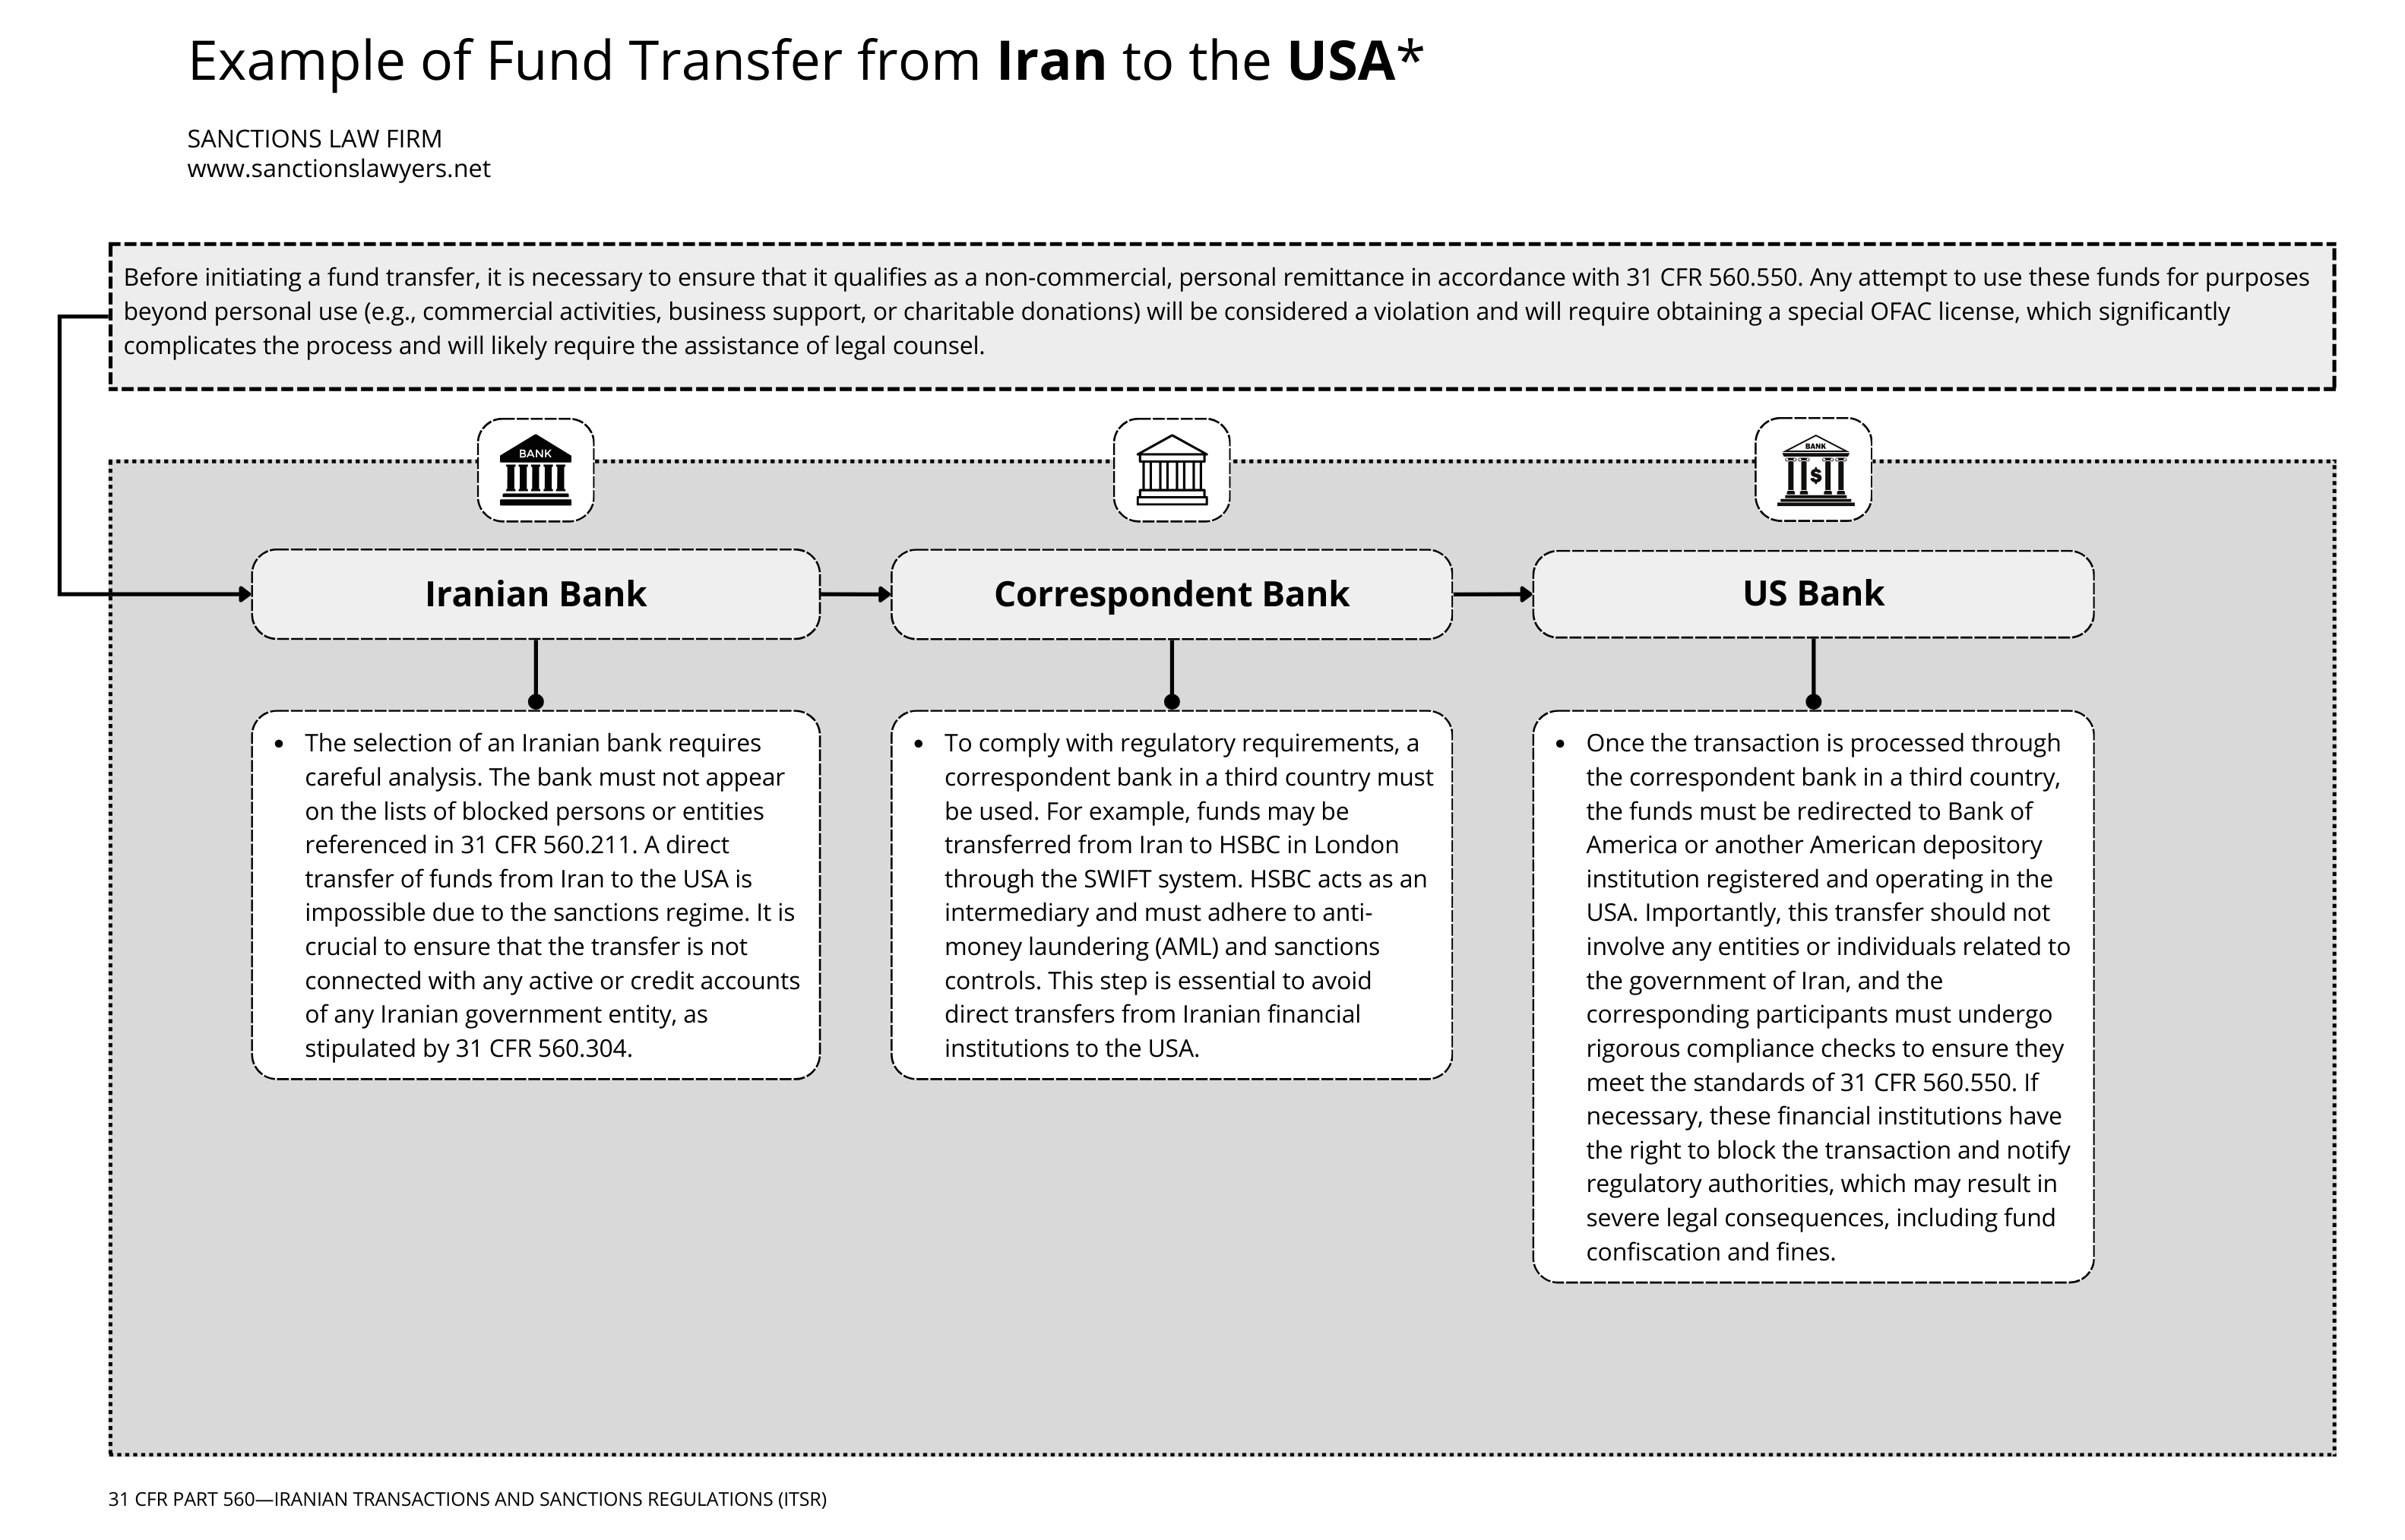
Wiring funds from Iran to the U.S
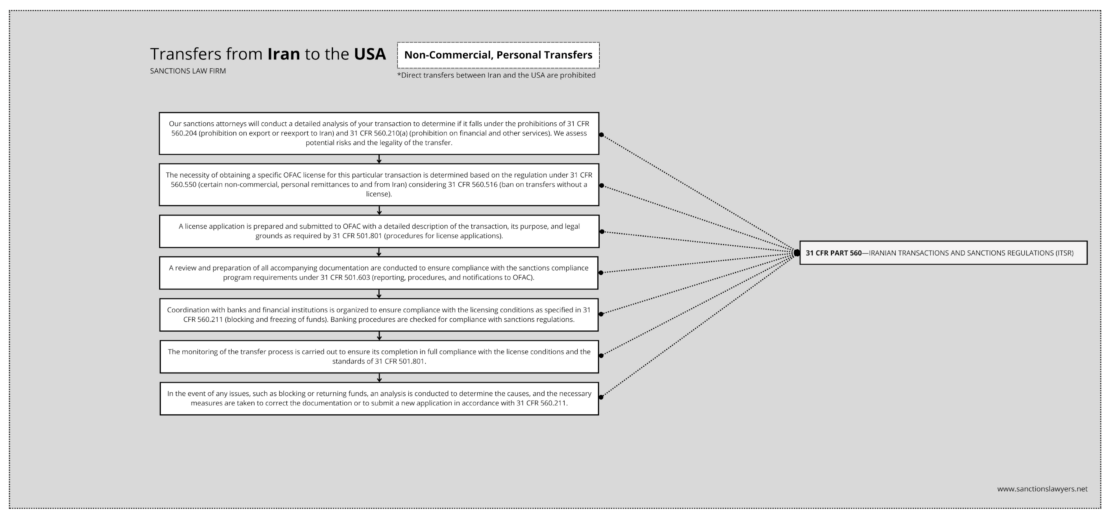
The first question anyone planning to wire funds from the country of Iran to the United States asks is: what is permitted, and what is not? The answer to this question lies in 31 CFR § 560.550. According to this provision, non-commercial, personal remittances between the U.S. and Iran (such as family support) are permitted, provided they comply with strict requirements. Transfers transferring money from iran to may only be conducted through registered U.S. depository institutions, exchange or securities broker-dealers.
The primary objective is to prevent situations where funds originating from Iran could be used to finance prohibited activities or organizations. For this reason, all transactions must be processed through verified countries and registered financial institutions. Attempts to bypass this system by using informal or shadow channels of exchange, such as Hawala, will immediately result in sanctions. In such cases, the other government or financial institution may block the transfer, and OFAC may initiate an investigation, which could lead to asset freezes and substantial fines.
Additionally, it is crucial for banks to remember that 31 CFR § 501.603 requires all financial institutions to immediately notify OFAC of any suspicious transactions. This provision underscores the necessity of strict adherence to all established procedures, as any violation will be treated as an attempt to circumvent the sanctions regime. If a bank determines that a customer’ transaction violates the sanctions, the bank and customer’ funds may be frozen, and recovering them may be extremely difficult, if not impossible.
ARE YOU PLANNING TO TRANSFER FUNDS FROM IRAN TO THE UNITED STATES OR ANOTHER COUNTRY? SEEK COUNSEL FROM SANCTIONS ATTORNEYS.
Is it possible to wire money to Iran?
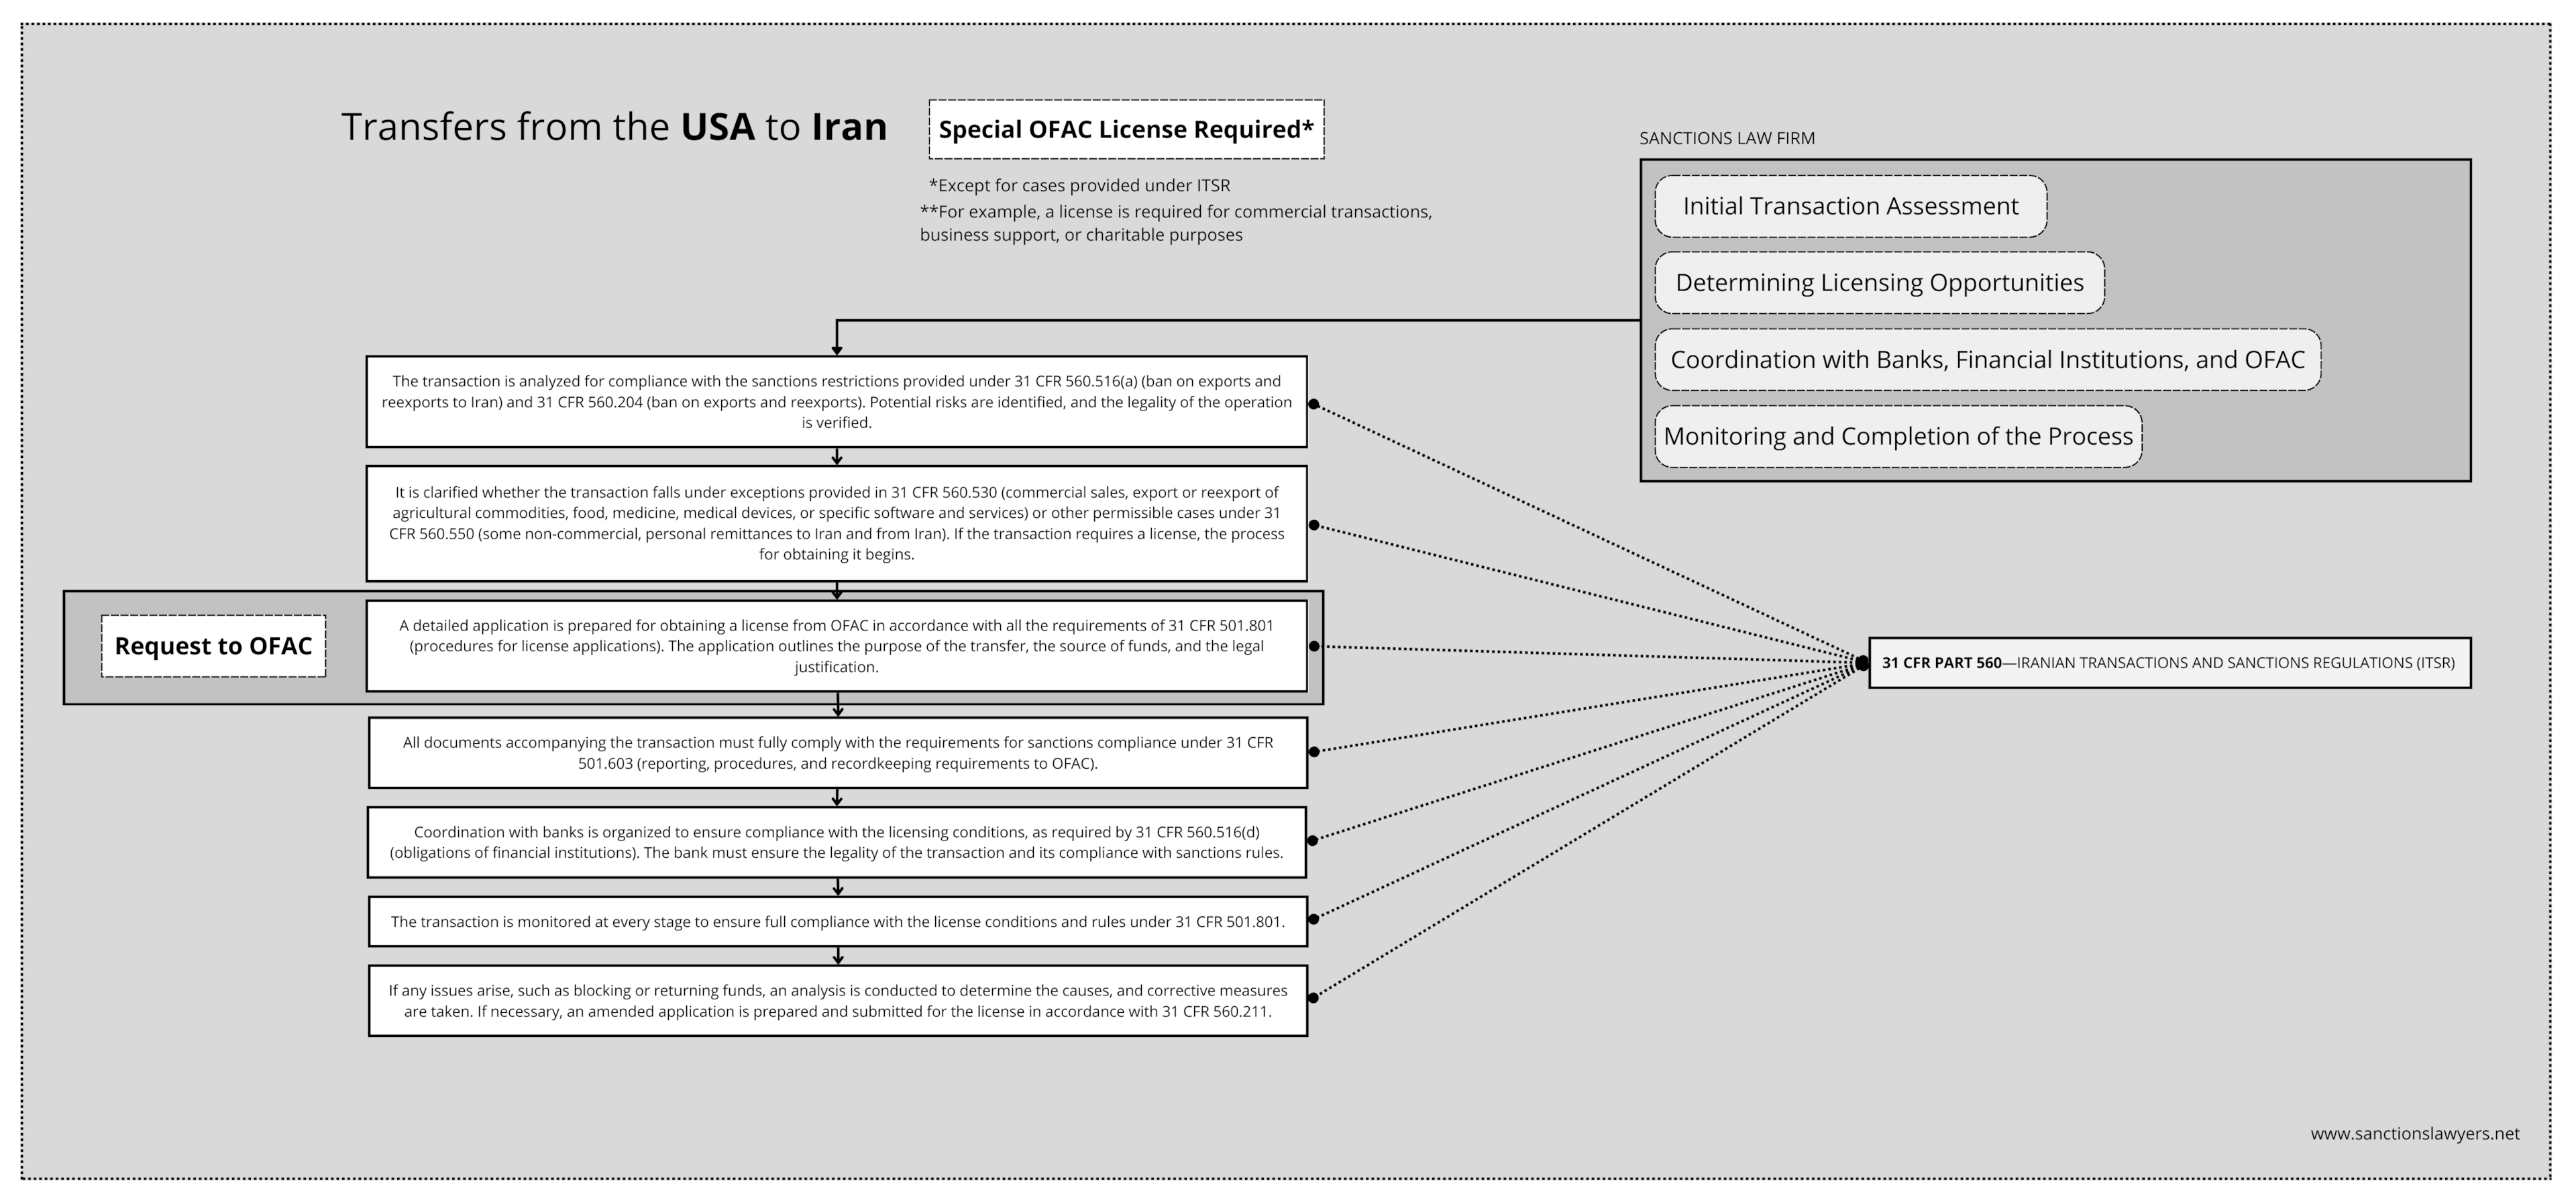
Transferring funds to Iran is a domain under particular scrutiny by U.S. regulators. According to 31 CFR § 560.516, all fund transfers to Iran are prohibited unless licensed by OFAC. Section 560.516 also allows for certain transactions but prohibits direct debiting or crediting of money laundering Iranian bank accounts. The rules concerning personal non-commercial money transfers as outlined earlier in 31 CFR § 560.550 are also applicable.
Exceptions for fund transfers to Iran do exist, but they primarily pertain to humanitarian purposes or payment for medical services, and even then, only after obtaining a Special License from OFAC. This includes transfers related to the commercial sale, export, re-export, and accompanying provision of services and software for agricultural products, medicine, medical devices, as well as replacement components and associated training services under the exceptional sanctions authorizations and restrictions provided in 31 CFR § 560.530. Additionally, transfer money transfers from certain countries to non-governmental organizations licensed by OFAC are permitted. The process of obtaining a license is highly complex and requires detailed justification and strict compliance with the established objectives. A license application must include comprehensive information about the purpose of the transfer, sources of funds, and provide a rationale that the transaction aligns with ofac regulations objectives (31 CFR § 501.801). If OFAC determines that the information provided is insufficient or does not meet the requirements, the application will be denied. In such a case, the entire process must be restarted, which can take months and require all parties involved’ significant time and resources.
An example of violations could involve a company attempting to send money to Iran under the guise of humanitarian aid but unable to prove that all funds will be used solely for medical purposes. In such a scenario, OFAC is likely to reject the recipient of the cash and license application, and the company and funds themselves may be frozen. Violating the rules established by 31 CFR § 560.516 will automatically result in the blocking of the transaction and the imposition of liability on the participants.
Moreover, even if you manage to obtain a specific license, you must be well aware and prepared for every step of your first account transfer to be closely monitored. Financial institutions and banks involved in the process are required to ensure compliance with all requirements, and be aware that any deviation from them will be immediately recorded and may result in further sanctions.
Compliance with OFAC sanctions
Compliance with the Iranian Transactions and Sanctions Regulations is not merely a formality; it is a critical requirement for anyone seeking to avoid serious legal consequences. 31 CFR Part 501 establishes stringent standards for all entities subject to sanctions imposed by U.S. jurisdiction. Violations of these standards can lead to significant fines and criminal prosecution. One of the most important aspects of sanctions compliance is having an effective compliance program in place. Such a program should include regular audits and checks for adherence to sanctions laws and requirements and the development of procedures for identifying and blocking suspicious transactions. Companies and banks are obligated to regularly audit their operations to ensure they comply with the requirements of 31 CFR Part 560. Any violations identified during such an audit can result in serious consequences.
What to do, if Funds are Returned
Imagine a scenario where your funds are returned, and you do not understand why. This can only mean one thing — something went wrong, and you need to take immediate action. 31 CFR § 560.211 requires that any assets associated with entities together with a sanctions violation be frozen. The reasons for the return transferring money can vary, but most often it is related to the absence of a license or errors in documentation. If you do not take action immediately, the risk is the situation will only worsen.
Your first step should be to consult with your bank or an attorney who understands the nuances of the Iranian Transactions and Sanctions Regulations. It is necessary to properly submit a license application, as regulated by 31 CFR § 501.801, or seek clarification from general license, for financial institutions. However, you and bank must be prepared for a complex process requiring precise justification that the transaction is legal and that any alleged violations were unintentional. Ignoring the issue will lead to even more severe consequences.
Personal Remittances to Iran — What OFAC Allows
Under the Iran sanctions framework (31 CFR Part 560), OFAC has issued general licenses that automatically authorize personal remittances without requiring individual applications. These are among the few types of transfers that U.S. persons can legally make to Iran without a specific license. Here is what qualifies:
What Counts as a Personal Remittance
A personal remittance under OFAC rules is a non-commercial transfer of funds to a close family member in Iran intended for personal or household expenses. This includes:
- Monthly family support payments (living expenses, medical care, education)
- One-time monetary gifts for personal use
- Funds for family members’ travel outside Iran
- Inherited cash or funds from the sale of property acquired before the sender immigrated to the United States
- Proceeds from selling inherited property in Iran (where no SDN-listed party is involved)
What Is Not Covered by the General License
The general license for personal remittances does not cover:
- Any transfer that benefits the Iranian government, state-owned entities, or the Central Bank of Iran
- Transfers to individuals or entities on OFAC’s SDN list
- Charitable donations (these require a separate specific license)
- Business-related transfers, even to family members who operate businesses
- Payments for real estate purchased after the sender moved to the United States
The SDN Check: Non-Negotiable
Before any transfer — even a personal remittance — you must verify that no party involved (sender, recipient, intermediary bank) appears on OFAC’s Specially Designated Nationals (SDN) list. A single SDN-listed intermediary bank in the chain can make an otherwise-legal transfer illegal. Our attorneys conduct full SDN screening as part of any Iran transfer consultation. Learn more about SDN list removal if a party has been designated.
How Routing Works: Third-Country Banks
Direct transfers between U.S. banks and Iranian banks are prohibited. Even if your transfer is authorized under a general license, it must route through a bank in a third country — typically Turkey, UAE, or an EU country — that maintains correspondent banking relationships with Iran. U.S. financial institutions are prohibited from processing such transactions directly. This routing complexity is why even fully legal remittances often require legal guidance.
How to Get an OFAC License for Iran Transfers
When your transfer falls outside the automatic general license categories — commercial transactions, post-immigration property sales, large estate transfers, or any payment involving unique circumstances — you must apply for an OFAC-specific license (also called a “specific license” or “special license”). Here is how the process works:
Step 1: Determine Whether a Specific License Is Required
Start by checking whether your transaction is already covered by a general license under 31 CFR Part 560. Many personal remittances and humanitarian transfers do not require a separate application. However, if your transfer involves:
- Property purchased in Iran after immigrating to the United States
- Business transactions or commercial payments
- Movable property received as a gift in Iran
- Closing a bank account in Iran and transferring the balance
- Any transaction involving a blocked entity or unusual party structure
…you will need a specific license from OFAC.
Step 2: Prepare Your Application
OFAC specific license applications are submitted through the agency’s online portal (ofac.treasury.gov). A complete application includes:
- Full identification of all parties (sender, recipient, financial institutions)
- Detailed description of the transaction, purpose, and dollar amount
- Supporting documents (contracts, estate documents, property records, bank statements)
- Legal basis for why the transaction should be authorized
- Compliance certifications confirming no SDN involvement
Incomplete or poorly documented applications are routinely denied. An experienced OFAC licensing attorney significantly increases your approval rate by framing the application correctly and anticipating OFAC’s review criteria.
Step 3: OFAC Review Timeline
OFAC does not publish fixed processing times. Simple cases involving personal remittances or estate matters may be resolved in 4–8 weeks. Complex commercial transactions or cases involving parties with any SDN proximity can take several months. OFAC may request additional documentation (“supplemental information request”) during review, which extends the timeline.
Step 4: Compliance After Approval
An approved specific license is not a blank check. It authorizes a specific transaction under specified conditions. You must comply with all license terms, maintain records of the transaction for at least 5 years (OFAC record retention requirement), and report the transaction if required. Violating license conditions is itself an OFAC violation.
Which Services Can Send Money to Iran?
This is the most common practical question — and the answer is complicated. Major money transfer operators are generally not available for Iran transfers due to the broad U.S. sanctions framework.
Western Union, Wise, and Remitly
Western Union, Wise, and Remitly do not offer direct transfers to Iran from the United States. All three are U.S.-regulated entities and cannot process Iran transfers without an OFAC export service license under 31 CFR § 560.418. None of these companies currently hold such licenses for personal remittances to Iran. If you see third-party services claiming to facilitate transfers through these platforms to Iran, treat this as a significant compliance red flag.
Third-Country Intermediary Banks and Exchange Offices
The most common legal mechanism for personal remittances to Iran involves:
- Third-country exchange houses in Turkey, UAE, or EU countries that are authorized to receive USD and convert to Iranian rial (IRR) for delivery to recipients in Iran
- Iranian exchange offices abroad — some operate legally in countries with active banking ties to Iran, though vetting is critical
- Correspondent banking through non-U.S. financial institutions — a U.S. person sends funds to a non-U.S. bank account, which then routes to Iran via an authorized Iranian bank not on the SDN list
The key compliance requirement: no U.S. financial institution may directly process the Iran-side of the transaction. The routing must stay outside the U.S. financial system once funds exit the sender’s account.
Hawala and Informal Transfers
Hawala networks are widely used for Iran remittances, but their legal status is precarious. Under 31 CFR §§ 560.204 and 560.206, U.S. persons are prohibited from exporting financial services to Iran without OFAC authorization — and hawala operators who lack licenses are providing unauthorized financial services. While hawala may seem practical, it exposes U.S. senders to significant enforcement risk. OFAC has actively pursued enforcement actions against unlicensed informal value transfer operators. A specific OFAC license is required to use a hawala network for Iran transfers legally, and approvals are rare.
Cryptocurrency Transfers
Cryptocurrency is not a sanctions workaround. OFAC has explicitly stated that sanctions prohibitions apply equally to digital currency transactions. If you transfer crypto to a wallet controlled by a sanctioned Iranian entity or individual, you are in violation regardless of the payment method. OFAC actively monitors blockchain activity and has sanctioned crypto addresses tied to Iranian entities. Using crypto for Iran transfers without a specific OFAC license carries the same legal exposure as any other unauthorized transfer.
Penalties for Illegal Transfers to Iran
OFAC Iran sanctions violations carry severe consequences. Under IEEPA and ITSR:
- Civil penalties: Up to $377,700 per violation or twice the transaction value (whichever is greater)
- Criminal penalties: Up to 20 years imprisonment and $1,000,000 in fines per violation
- Corporate liability: Financial institutions that process unauthorized Iran transfers face penalties, license revocations, and reputational damage
- No intent requirement for civil violations: OFAC can impose civil penalties even for “good faith” transfers that technically violate the rules
OFAC issued 14 enforcement actions in 2025, with Iran-related cases consistently among the highest-value penalties. Voluntary self-disclosure of violations typically results in significantly reduced penalties — another reason to consult an attorney before and after any Iran transfer.
Need Help With an OFAC License for Iran?
Iran money transfer cases are among the most technically complex areas of OFAC practice. The difference between a legal remittance and an OFAC violation can come down to a single party’s SDN status, the routing bank used, or a missing document. Our OFAC licensing lawyers have handled Iran-related remittances, estate transfers, business wind-downs, and specific license applications across dozens of cases.
We can help you:
- Determine whether your transfer qualifies under an existing general license
- Conduct full SDN screening of all parties in the transaction chain
- Draft and submit an OFAC specific license application
- Respond to OFAC supplemental information requests
- Advise on compliant routing through third-country financial institutions
- Handle OFAC enforcement defense if a violation has already occurred
OFAC General Licenses for Iran: What Transactions Are Permitted
The U.S. Treasury’s Office of Foreign Assets Control (OFAC) maintains a set of general licenses under the Iranian Transactions and Sanctions Regulations (31 CFR Part 560) that authorize specific categories of money transfers to Iran without requiring individual license applications. Understanding which category your transaction falls into is the critical first step. The table below summarizes the currently active general license categories for Iran-related financial transfers as of 2025–2026.
| License Category | What’s Permitted | Key Conditions | License Type |
|---|---|---|---|
| Personal Remittances to Family | Sending money to close family members in Iran for personal/household expenses, living costs, medical care, and education | Non-commercial purpose only; no SDN-listed recipients; must route through non-U.S. financial institution; no fixed dollar cap | General License (automatic) — 31 CFR § 560.550 |
| Educational Fees & Student Support | Tuition payments, academic fees, books, and living expenses for Iranian students studying outside Iran; educational materials to Iran | Payments must be for personal academic use; no benefit to Iranian government or state institutions; no commercial resale | General License (automatic) — 31 CFR § 560.550 |
| Humanitarian Transfers | Food, medicine, medical devices, and personal medical expenses; donations to recognized NGOs operating in Iran | Items/funds must meet OFAC humanitarian definition; NGO must not be SDN-listed; no dual-use goods; separate GL covers donations to charities (GL 8A related) | General License (automatic) — ITSR Humanitarian Provisions |
| Family Support — Inherited & Estate Funds | Transfer of inherited cash or proceeds from sale of property acquired before U.S. immigration; closing inherited bank accounts in Iran | Property must have been acquired before sender’s U.S. immigration; no SDN-listed parties in transaction; court/estate documentation required | General License (conditional) — specific license may be required for complex estates |
| Monetary Gifts (Non-Commercial) | One-time monetary gifts to individuals in Iran for personal use (weddings, emergencies, personal support) | No commercial purpose; recipient must not be SDN-listed or connected to Iranian government; no business investment | General License (automatic) — 31 CFR § 560.550 |
| Blocked Funds / Iranian Financial Institutions | Certain transactions involving Iranian financial institutions blocked under Executive Order 13902 (Iran General License L) | Narrow scope; applies to specific authorized financial institutions only; legal counsel strongly advised | Iran General License L (issued Oct. 2020) |
| Post-Immigration Property Sales | Proceeds from selling property in Iran acquired after the sender immigrated to the U.S. | Specific OFAC license required — not covered by general license; application must document full transaction history | Specific License Required |
| Business & Commercial Payments | Not permitted under any general license; requires specific OFAC license (rarely granted) | Prohibited for virtually all U.S. persons and companies; specific license process can take 6+ months | Specific License Required (rarely approved) |
Important: Even transactions covered by a general license may be blocked if any party in the transfer chain — sender, recipient, intermediary bank, or exchange house — appears on OFAC’s Specially Designated Nationals (SDN) list. Always conduct full SDN screening before proceeding. Our OFAC licensing attorneys provide SDN screening as part of every consultation.
Iran Money Transfer: Frequently Asked Questions
The following questions are among the most common we receive from individuals and families navigating Iran money transfer rules. Each answer reflects current OFAC regulations under 31 CFR Part 560 as of 2025–2026.
Can I send money to my family in Iran?
Yes — personal remittances to close family members in Iran are permitted under OFAC General License (31 CFR § 560.550) without requiring a separate application. You may send funds for living expenses, medical care, and education. The transfer must be non-commercial, must not benefit SDN-listed individuals, and must route through a third-country bank (not directly through U.S. financial institutions).
Which banks process Iran money transfers legally?
No major U.S. bank can directly process transfers to Iran — U.S. financial institutions are prohibited from serving as the direct conduit for Iran-side transactions. Legal transfers typically route through banks in Turkey, the UAE, Germany, or other countries that maintain correspondent banking relationships with Iranian banks not on the SDN list. Non-U.S. banks such as certain Turkish and UAE institutions may facilitate the Iran leg of the transfer, but you must verify their SDN status. Using an OFAC-experienced attorney to identify compliant routing is strongly recommended.
What is the maximum amount I can send to Iran?
There is no fixed dollar cap for personal remittances under the OFAC general license (31 CFR § 560.550). However, larger transfers attract greater scrutiny. The transfer must be for personal/household purposes — not investment, business, or commercial use. Transfers above certain thresholds may trigger Bank Secrecy Act (BSA) reporting requirements (e.g., Currency Transaction Reports for amounts over $10,000). For large remittances, we strongly advise obtaining a legal opinion confirming compliance before proceeding.
Can I send money to Iran for educational fees?
Yes — educational fees and student support payments fall within the personal remittances general license under 31 CFR § 560.550. This covers tuition payments, academic fees, books, and living expenses for Iranian students. The key condition is that the payment must be for personal academic use — not to Iranian state educational institutions (which may be SDN-linked). Payments to private universities or educational institutions outside Iran on behalf of Iranian students are generally permissible.
Is Western Union available for sending money to Iran?
No — Western Union, Wise, Remitly, and most major money transfer operators do not offer direct transfers to Iran from the U.S. These companies are U.S.-regulated entities and cannot process Iran-side transactions without an OFAC export service license (31 CFR § 560.418), which none currently hold for personal remittances. Transfers must instead route through authorized third-country exchange houses or correspondent banking channels. Be cautious of services claiming to offer Western Union or Wise-based Iran transfers — these are compliance red flags.
Do I need an OFAC license to send humanitarian aid to Iran?
Not always — many humanitarian transfers are covered under existing general licenses. Food, medicine, medical devices, and personal medical expenses are authorized under ITSR humanitarian provisions without a specific license application. However, charitable donations to organizations operating in Iran require a specific license, as does any transfer that benefits an Iranian government entity or SDN-listed organization. If you are sending funds through an NGO or charity, confirm their licensing status before transferring.
What happens if I accidentally send money illegally to Iran?
Even accidental or good-faith violations of Iran sanctions can result in civil penalties of up to $377,700 per violation (or twice the transaction value) (or twice the transaction value). OFAC does not require intent for civil violations. If you have already made a transfer that may violate sanctions, the most important immediate step is voluntary self-disclosure — which typically results in significantly reduced penalties. Contact an OFAC attorney immediately to assess your exposure and prepare a disclosure if needed.
Wire Transfers to Iran: What Is Permitted vs. Prohibited
| Transfer Type | Status | Conditions |
|---|---|---|
| Family remittances (personal) | Permitted (general license) | To non-SDN family members; personal use only |
| Humanitarian payments (food, medicine) | Permitted (general license) | Not to Iranian government; authorized recipients only |
| Legal services fees | Permitted (general license) | Payment for legal representation in U.S. proceedings |
| Dollar-denominated commercial transfers | Prohibited | Blocked by U.S. correspondent banks |
| Transfers to Iranian government entities | Prohibited | Includes Central Bank of Iran |
| Transfers to SDN-listed individuals/entities | Prohibited | Full asset block applies |
| OFAC-licensed specific transactions | Permitted with licence | Requires prior OFAC specific licence application |
Conducting business in a global economy often has risk and requires flexibility and the ability to quickly adapt to changing conditions. However, when it comes to financial transactions involving Iran, caution is paramount. The Iran sanctions regime established by the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) leaves no room for error. Any deviation from established norms can lead to severe consequences, including asset freezes and criminal prosecution. The detailed regulations set forth in sanctions programs 31 CFR Part 560 (Iranian Transactions and Sanctions Regulations, ITSR) are the key aspect of conducting any transactions involving Iran. If you are planning to wire transfer from Iran to the United States or other countries or vice versa, this process will require not only knowledge but also legal support at every stage of underlying transaction.
Wiring funds from Iran to the U.S
The first question anyone planning to wire funds from the country of Iran to the United States asks is: what is permitted, and what is not? The answer to this question lies in 31 CFR § 560.550. According to this provision, non-commercial, personal remittances between the U.S. and Iran (such as family support) are permitted, provided they comply with strict requirements. Transfers transferring money from iran to may only be conducted through registered U.S. depository institutions, exchange or securities broker-dealers.
The primary objective is to prevent situations where funds originating from Iran could be used to finance prohibited activities or organizations. For this reason, all transactions must be processed through verified countries and registered financial institutions. Attempts to bypass this system by using informal or shadow channels of exchange, such as Hawala, will immediately result in sanctions. In such cases, the other government or financial institution may block the transfer, and OFAC may initiate an investigation, which could lead to asset freezes and substantial fines.
Additionally, it is crucial for banks to remember that 31 CFR § 501.603 requires all financial institutions to immediately notify OFAC of any suspicious transactions. This provision underscores the necessity of strict adherence to all established procedures, as any violation will be treated as an attempt to circumvent the sanctions regime. If a bank determines that a customer’ transaction violates the sanctions, the bank and customer’ funds may be frozen, and recovering them may be extremely difficult, if not impossible.
ARE YOU PLANNING TO TRANSFER FUNDS FROM IRAN TO THE UNITED STATES OR ANOTHER COUNTRY? SEEK COUNSEL FROM SANCTIONS ATTORNEYS.
Is it possible to wire money to Iran?
Transferring funds to Iran is a domain under particular scrutiny by U.S. regulators. According to 31 CFR § 560.516, all fund transfers to Iran are prohibited unless licensed by OFAC. Section 560.516 also allows for certain transactions but prohibits direct debiting or crediting of money laundering Iranian bank accounts. The rules concerning personal non-commercial money transfers as outlined earlier in 31 CFR § 560.550 are also applicable.
Exceptions for fund transfers to Iran do exist, but they primarily pertain to humanitarian purposes or payment for medical services, and even then, only after obtaining a Special License from OFAC. This includes transfers related to the commercial sale, export, re-export, and accompanying provision of services and software for agricultural products, medicine, medical devices, as well as replacement components and associated training services under the exceptional sanctions authorizations and restrictions provided in 31 CFR § 560.530. Additionally, transfer money transfers from certain countries to non-governmental organizations licensed by OFAC are permitted. The process of obtaining a license is highly complex and requires detailed justification and strict compliance with the established objectives. A license application must include comprehensive information about the purpose of the transfer, sources of funds, and provide a rationale that the transaction aligns with ofac regulations objectives (31 CFR § 501.801). If OFAC determines that the information provided is insufficient or does not meet the requirements, the application will be denied. In such a case, the entire process must be restarted, which can take months and require all parties involved’ significant time and resources.
An example of violations could involve a company attempting to send money to Iran under the guise of humanitarian aid but unable to prove that all funds will be used solely for medical purposes. In such a scenario, OFAC is likely to reject the recipient of the cash and license application, and the company and funds themselves may be frozen. Violating the rules established by 31 CFR § 560.516 will automatically result in the blocking of the transaction and the imposition of liability on the participants.
Moreover, even if you manage to obtain a specific license, you must be well aware and prepared for every step of your first account transfer to be closely monitored. Financial institutions and banks involved in the process are required to ensure compliance with all requirements, and be aware that any deviation from them will be immediately recorded and may result in further sanctions.
Compliance with OFAC sanctions
Compliance with the Iranian Transactions and Sanctions Regulations is not merely a formality; it is a critical requirement for anyone seeking to avoid serious legal consequences. 31 CFR Part 501 establishes stringent standards for all entities subject to sanctions imposed by U.S. jurisdiction. Violations of these standards can lead to significant fines and criminal prosecution. One of the most important aspects of sanctions compliance is having an effective compliance program in place. Such a program should include regular audits and checks for adherence to sanctions laws and requirements and the development of procedures for identifying and blocking suspicious transactions. Companies and banks are obligated to regularly audit their operations to ensure they comply with the requirements of 31 CFR Part 560. Any violations identified during such an audit can result in serious consequences.
What to do, if Funds are Returned
Imagine a scenario where your funds are returned, and you do not understand why. This can only mean one thing — something went wrong, and you need to take immediate action. 31 CFR § 560.211 requires that any assets associated with entities together with a sanctions violation be frozen. The reasons for the return transferring money can vary, but most often it is related to the absence of a license or errors in documentation. If you do not take action immediately, the risk is the situation will only worsen.
Your first step should be to consult with your bank or an attorney who understands the nuances of the Iranian Transactions and Sanctions Regulations. It is necessary to properly submit a license application, as regulated by 31 CFR § 501.801, or seek clarification from general license, for financial institutions. However, you and bank must be prepared for a complex process requiring precise justification that the transaction is legal and that any alleged violations were unintentional. Ignoring the issue will lead to even more severe consequences.
Key Legal Options at a Glance
- Personal remittances to family — Permitted under OFAC General License (31 CFR § 560.550). No fixed dollar cap, but no commercial purpose allowed.
- Humanitarian transfers — Authorized for food, medicine, and personal medical expenses under separate GL provisions.
- Inherited funds and property proceeds — Permitted via GL when no SDN-listed parties are involved; must route through a third-country bank.
- Business payments, commercial transfers — Prohibited unless you hold an OFAC-specific license.
- All transfers — Must bypass SDN-listed individuals and entities, Iranian government bodies, and the Central Bank of Iran.
Legal vs. Illegal: Iran Money Transfers at a Glance
| Transaction Type | Legal Status | Authorization Required | Risk Level |
|---|---|---|---|
| Personal remittances to close family | ✅ Legal | General License (automatic) | Low if documented |
| Monetary gifts to individuals (non-commercial) | ✅ Legal | General License (automatic) | Low if documented |
| Humanitarian transfers (food, medicine) | ✅ Legal | General License (automatic) | Low |
| Inherited funds / property proceeds | ⚠️ Conditional | General License; no SDN parties | Medium — verify all parties |
| Property sold after immigrating to USA | ⚠️ Specific License | Specific OFAC license required | High without license |
| Business payments to Iranian companies | ❌ Prohibited | Specific license (rarely granted) | Very High |
| Payments to Iranian government entities | ❌ Prohibited | Not licensable in most cases | Critical |
| Payments to SDN-listed individuals | ❌ Prohibited | Not licensable | Critical — criminal exposure |
| Hawala / informal transfers without OFAC license | ❌ Prohibited | Specific license required | Very High — active enforcement |
| Cryptocurrency transfers to sanctioned entities | ❌ Prohibited | Not licensable | Very High — OFAC tracks blockchain |
Personal Remittances to Iran — What OFAC Allows
Under the Iran sanctions framework (31 CFR Part 560), OFAC has issued general licenses that automatically authorize personal remittances without requiring individual applications. These are among the few types of transfers that U.S. persons can legally make to Iran without a specific license. Here is what qualifies:
What Counts as a Personal Remittance
A personal remittance under OFAC rules is a non-commercial transfer of funds to a close family member in Iran intended for personal or household expenses. This includes:
- Monthly family support payments (living expenses, medical care, education)
- One-time monetary gifts for personal use
- Funds for family members’ travel outside Iran
- Inherited cash or funds from the sale of property acquired before the sender immigrated to the United States
- Proceeds from selling inherited property in Iran (where no SDN-listed party is involved)
What Is Not Covered by the General License
The general license for personal remittances does not cover:
- Any transfer that benefits the Iranian government, state-owned entities, or the Central Bank of Iran
- Transfers to individuals or entities on OFAC’s SDN list
- Charitable donations (these require a separate specific license)
- Business-related transfers, even to family members who operate businesses
- Payments for real estate purchased after the sender moved to the United States
The SDN Check: Non-Negotiable
Before any transfer — even a personal remittance — you must verify that no party involved (sender, recipient, intermediary bank) appears on OFAC’s Specially Designated Nationals (SDN) list. A single SDN-listed intermediary bank in the chain can make an otherwise-legal transfer illegal. Our attorneys conduct full SDN screening as part of any Iran transfer consultation. Learn more about SDN list removal if a party has been designated.
How Routing Works: Third-Country Banks
Direct transfers between U.S. banks and Iranian banks are prohibited. Even if your transfer is authorized under a general license, it must route through a bank in a third country — typically Turkey, UAE, or an EU country — that maintains correspondent banking relationships with Iran. U.S. financial institutions are prohibited from processing such transactions directly. This routing complexity is why even fully legal remittances often require legal guidance.
How to Get an OFAC License for Iran Transfers
When your transfer falls outside the automatic general license categories — commercial transactions, post-immigration property sales, large estate transfers, or any payment involving unique circumstances — you must apply for an OFAC-specific license (also called a “specific license” or “special license”). Here is how the process works:
Step 1: Determine Whether a Specific License Is Required
Start by checking whether your transaction is already covered by a general license under 31 CFR Part 560. Many personal remittances and humanitarian transfers do not require a separate application. However, if your transfer involves:
- Property purchased in Iran after immigrating to the United States
- Business transactions or commercial payments
- Movable property received as a gift in Iran
- Closing a bank account in Iran and transferring the balance
- Any transaction involving a blocked entity or unusual party structure
…you will need a specific license from OFAC.
Step 2: Prepare Your Application
OFAC specific license applications are submitted through the agency’s online portal (ofac.treasury.gov). A complete application includes:
- Full identification of all parties (sender, recipient, financial institutions)
- Detailed description of the transaction, purpose, and dollar amount
- Supporting documents (contracts, estate documents, property records, bank statements)
- Legal basis for why the transaction should be authorized
- Compliance certifications confirming no SDN involvement
Incomplete or poorly documented applications are routinely denied. An experienced OFAC licensing attorney significantly increases your approval rate by framing the application correctly and anticipating OFAC’s review criteria.
Step 3: OFAC Review Timeline
OFAC does not publish fixed processing times. Simple cases involving personal remittances or estate matters may be resolved in 4–8 weeks. Complex commercial transactions or cases involving parties with any SDN proximity can take several months. OFAC may request additional documentation (“supplemental information request”) during review, which extends the timeline.
Step 4: Compliance After Approval
An approved specific license is not a blank check. It authorizes a specific transaction under specified conditions. You must comply with all license terms, maintain records of the transaction for at least 5 years (OFAC record retention requirement), and report the transaction if required. Violating license conditions is itself an OFAC violation.
Which Services Can Send Money to Iran?
This is the most common practical question — and the answer is complicated. Major money transfer operators are generally not available for Iran transfers due to the broad U.S. sanctions framework.
Western Union, Wise, and Remitly
Western Union, Wise, and Remitly do not offer direct transfers to Iran from the United States. All three are U.S.-regulated entities and cannot process Iran transfers without an OFAC export service license under 31 CFR § 560.418. None of these companies currently hold such licenses for personal remittances to Iran. If you see third-party services claiming to facilitate transfers through these platforms to Iran, treat this as a significant compliance red flag.
Third-Country Intermediary Banks and Exchange Offices
The most common legal mechanism for personal remittances to Iran involves:
- Third-country exchange houses in Turkey, UAE, or EU countries that are authorized to receive USD and convert to Iranian rial (IRR) for delivery to recipients in Iran
- Iranian exchange offices abroad — some operate legally in countries with active banking ties to Iran, though vetting is critical
- Correspondent banking through non-U.S. financial institutions — a U.S. person sends funds to a non-U.S. bank account, which then routes to Iran via an authorized Iranian bank not on the SDN list
The key compliance requirement: no U.S. financial institution may directly process the Iran-side of the transaction. The routing must stay outside the U.S. financial system once funds exit the sender’s account.
Hawala and Informal Transfers
Hawala networks are widely used for Iran remittances, but their legal status is precarious. Under 31 CFR §§ 560.204 and 560.206, U.S. persons are prohibited from exporting financial services to Iran without OFAC authorization — and hawala operators who lack licenses are providing unauthorized financial services. While hawala may seem practical, it exposes U.S. senders to significant enforcement risk. OFAC has actively pursued enforcement actions against unlicensed informal value transfer operators. A specific OFAC license is required to use a hawala network for Iran transfers legally, and approvals are rare.
Cryptocurrency Transfers
Cryptocurrency is not a sanctions workaround. OFAC has explicitly stated that sanctions prohibitions apply equally to digital currency transactions. If you transfer crypto to a wallet controlled by a sanctioned Iranian entity or individual, you are in violation regardless of the payment method. OFAC actively monitors blockchain activity and has sanctioned crypto addresses tied to Iranian entities. Using crypto for Iran transfers without a specific OFAC license carries the same legal exposure as any other unauthorized transfer.
Penalties for Illegal Transfers to Iran
OFAC Iran sanctions violations carry severe consequences. Under IEEPA and ITSR:
- Civil penalties: Up to $377,700 per violation or twice the transaction value (whichever is greater)
- Criminal penalties: Up to 20 years imprisonment and $1,000,000 in fines per violation
- Corporate liability: Financial institutions that process unauthorized Iran transfers face penalties, license revocations, and reputational damage
- No intent requirement for civil violations: OFAC can impose civil penalties even for “good faith” transfers that technically violate the rules
OFAC issued 14 enforcement actions in 2025, with Iran-related cases consistently among the highest-value penalties. Voluntary self-disclosure of violations typically results in significantly reduced penalties — another reason to consult an attorney before and after any Iran transfer.
Need Help With an OFAC License for Iran?
Iran money transfer cases are among the most technically complex areas of OFAC practice. The difference between a legal remittance and an OFAC violation can come down to a single party’s SDN status, the routing bank used, or a missing document. Our OFAC licensing lawyers have handled Iran-related remittances, estate transfers, business wind-downs, and specific license applications across dozens of cases.
We can help you:
- Determine whether your transfer qualifies under an existing general license
- Conduct full SDN screening of all parties in the transaction chain
- Draft and submit an OFAC specific license application
- Respond to OFAC supplemental information requests
- Advise on compliant routing through third-country financial institutions
- Handle OFAC enforcement defense if a violation has already occurred
OFAC General Licenses for Iran: What Transactions Are Permitted
The U.S. Treasury’s Office of Foreign Assets Control (OFAC) maintains a set of general licenses under the Iranian Transactions and Sanctions Regulations (31 CFR Part 560) that authorize specific categories of money transfers to Iran without requiring individual license applications. Understanding which category your transaction falls into is the critical first step. The table below summarizes the currently active general license categories for Iran-related financial transfers as of 2025–2026.
| License Category | What’s Permitted | Key Conditions | License Type |
|---|---|---|---|
| Personal Remittances to Family | Sending money to close family members in Iran for personal/household expenses, living costs, medical care, and education | Non-commercial purpose only; no SDN-listed recipients; must route through non-U.S. financial institution; no fixed dollar cap | General License (automatic) — 31 CFR § 560.550 |
| Educational Fees & Student Support | Tuition payments, academic fees, books, and living expenses for Iranian students studying outside Iran; educational materials to Iran | Payments must be for personal academic use; no benefit to Iranian government or state institutions; no commercial resale | General License (automatic) — 31 CFR § 560.550 |
| Humanitarian Transfers | Food, medicine, medical devices, and personal medical expenses; donations to recognized NGOs operating in Iran | Items/funds must meet OFAC humanitarian definition; NGO must not be SDN-listed; no dual-use goods; separate GL covers donations to charities (GL 8A related) | General License (automatic) — ITSR Humanitarian Provisions |
| Family Support — Inherited & Estate Funds | Transfer of inherited cash or proceeds from sale of property acquired before U.S. immigration; closing inherited bank accounts in Iran | Property must have been acquired before sender’s U.S. immigration; no SDN-listed parties in transaction; court/estate documentation required | General License (conditional) — specific license may be required for complex estates |
| Monetary Gifts (Non-Commercial) | One-time monetary gifts to individuals in Iran for personal use (weddings, emergencies, personal support) | No commercial purpose; recipient must not be SDN-listed or connected to Iranian government; no business investment | General License (automatic) — 31 CFR § 560.550 |
| Blocked Funds / Iranian Financial Institutions | Certain transactions involving Iranian financial institutions blocked under Executive Order 13902 (Iran General License L) | Narrow scope; applies to specific authorized financial institutions only; legal counsel strongly advised | Iran General License L (issued Oct. 2020) |
| Post-Immigration Property Sales | Proceeds from selling property in Iran acquired after the sender immigrated to the U.S. | Specific OFAC license required — not covered by general license; application must document full transaction history | Specific License Required |
| Business & Commercial Payments | Not permitted under any general license; requires specific OFAC license (rarely granted) | Prohibited for virtually all U.S. persons and companies; specific license process can take 6+ months | Specific License Required (rarely approved) |
Important: Even transactions covered by a general license may be blocked if any party in the transfer chain — sender, recipient, intermediary bank, or exchange house — appears on OFAC’s Specially Designated Nationals (SDN) list. Always conduct full SDN screening before proceeding. Our OFAC licensing attorneys provide SDN screening as part of every consultation.
Iran Money Transfer: Frequently Asked Questions
The following questions are among the most common we receive from individuals and families navigating Iran money transfer rules. Each answer reflects current OFAC regulations under 31 CFR Part 560 as of 2025–2026.
Can I send money to my family in Iran?
Yes — personal remittances to close family members in Iran are permitted under OFAC General License (31 CFR § 560.550) without requiring a separate application. You may send funds for living expenses, medical care, and education. The transfer must be non-commercial, must not benefit SDN-listed individuals, and must route through a third-country bank (not directly through U.S. financial institutions).
Which banks process Iran money transfers legally?
No major U.S. bank can directly process transfers to Iran — U.S. financial institutions are prohibited from serving as the direct conduit for Iran-side transactions. Legal transfers typically route through banks in Turkey, the UAE, Germany, or other countries that maintain correspondent banking relationships with Iranian banks not on the SDN list. Non-U.S. banks such as certain Turkish and UAE institutions may facilitate the Iran leg of the transfer, but you must verify their SDN status. Using an OFAC-experienced attorney to identify compliant routing is strongly recommended.
What is the maximum amount I can send to Iran?
There is no fixed dollar cap for personal remittances under the OFAC general license (31 CFR § 560.550). However, larger transfers attract greater scrutiny. The transfer must be for personal/household purposes — not investment, business, or commercial use. Transfers above certain thresholds may trigger Bank Secrecy Act (BSA) reporting requirements (e.g., Currency Transaction Reports for amounts over $10,000). For large remittances, we strongly advise obtaining a legal opinion confirming compliance before proceeding.
Can I send money to Iran for educational fees?
Yes — educational fees and student support payments fall within the personal remittances general license under 31 CFR § 560.550. This covers tuition payments, academic fees, books, and living expenses for Iranian students. The key condition is that the payment must be for personal academic use — not to Iranian state educational institutions (which may be SDN-linked). Payments to private universities or educational institutions outside Iran on behalf of Iranian students are generally permissible.
Is Western Union available for sending money to Iran?
No — Western Union, Wise, Remitly, and most major money transfer operators do not offer direct transfers to Iran from the U.S. These companies are U.S.-regulated entities and cannot process Iran-side transactions without an OFAC export service license (31 CFR § 560.418), which none currently hold for personal remittances. Transfers must instead route through authorized third-country exchange houses or correspondent banking channels. Be cautious of services claiming to offer Western Union or Wise-based Iran transfers — these are compliance red flags.
Do I need an OFAC license to send humanitarian aid to Iran?
Not always — many humanitarian transfers are covered under existing general licenses. Food, medicine, medical devices, and personal medical expenses are authorized under ITSR humanitarian provisions without a specific license application. However, charitable donations to organizations operating in Iran require a specific license, as does any transfer that benefits an Iranian government entity or SDN-listed organization. If you are sending funds through an NGO or charity, confirm their licensing status before transferring.
What happens if I accidentally send money illegally to Iran?
Even accidental or good-faith violations of Iran sanctions can result in civil penalties of up to $377,700 per violation (or twice the transaction value) (or twice the transaction value). OFAC does not require intent for civil violations. If you have already made a transfer that may violate sanctions, the most important immediate step is voluntary self-disclosure — which typically results in significantly reduced penalties. Contact an OFAC attorney immediately to assess your exposure and prepare a disclosure if needed.
Wire Transfers to Iran: What Is Permitted vs. Prohibited
| Transfer Type | Status | Conditions |
|---|---|---|
| Family remittances (personal) | Permitted (general license) | To non-SDN family members; personal use only |
| Humanitarian payments (food, medicine) | Permitted (general license) | Not to Iranian government; authorized recipients only |
| Legal services fees | Permitted (general license) | Payment for legal representation in U.S. proceedings |
| Dollar-denominated commercial transfers | Prohibited | Blocked by U.S. correspondent banks |
| Transfers to Iranian government entities | Prohibited | Includes Central Bank of Iran |
| Transfers to SDN-listed individuals/entities | Prohibited | Full asset block applies |
| OFAC-licensed specific transactions | Permitted with licence | Requires prior OFAC specific licence application |
Conducting business in a global economy often has risk and requires flexibility and the ability to quickly adapt to changing conditions. However, when it comes to financial transactions involving Iran, caution is paramount. The Iran sanctions regime established by the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) leaves no room for error. Any deviation from established norms can lead to severe consequences, including asset freezes and criminal prosecution. The detailed regulations set forth in sanctions programs 31 CFR Part 560 (Iranian Transactions and Sanctions Regulations, ITSR) are the key aspect of conducting any transactions involving Iran. If you are planning to wire transfer from Iran to the United States or other countries or vice versa, this process will require not only knowledge but also legal support at every stage of underlying transaction.
Wiring funds from Iran to the U.S
The first question anyone planning to wire funds from the country of Iran to the United States asks is: what is permitted, and what is not? The answer to this question lies in 31 CFR § 560.550. According to this provision, non-commercial, personal remittances between the U.S. and Iran (such as family support) are permitted, provided they comply with strict requirements. Transfers transferring money from iran to may only be conducted through registered U.S. depository institutions, exchange or securities broker-dealers.
The primary objective is to prevent situations where funds originating from Iran could be used to finance prohibited activities or organizations. For this reason, all transactions must be processed through verified countries and registered financial institutions. Attempts to bypass this system by using informal or shadow channels of exchange, such as Hawala, will immediately result in sanctions. In such cases, the other government or financial institution may block the transfer, and OFAC may initiate an investigation, which could lead to asset freezes and substantial fines.
Additionally, it is crucial for banks to remember that 31 CFR § 501.603 requires all financial institutions to immediately notify OFAC of any suspicious transactions. This provision underscores the necessity of strict adherence to all established procedures, as any violation will be treated as an attempt to circumvent the sanctions regime. If a bank determines that a customer’ transaction violates the sanctions, the bank and customer’ funds may be frozen, and recovering them may be extremely difficult, if not impossible.
ARE YOU PLANNING TO TRANSFER FUNDS FROM IRAN TO THE UNITED STATES OR ANOTHER COUNTRY? SEEK COUNSEL FROM SANCTIONS ATTORNEYS.
Is it possible to wire money to Iran?
Transferring funds to Iran is a domain under particular scrutiny by U.S. regulators. According to 31 CFR § 560.516, all fund transfers to Iran are prohibited unless licensed by OFAC. Section 560.516 also allows for certain transactions but prohibits direct debiting or crediting of money laundering Iranian bank accounts. The rules concerning personal non-commercial money transfers as outlined earlier in 31 CFR § 560.550 are also applicable.
Exceptions for fund transfers to Iran do exist, but they primarily pertain to humanitarian purposes or payment for medical services, and even then, only after obtaining a Special License from OFAC. This includes transfers related to the commercial sale, export, re-export, and accompanying provision of services and software for agricultural products, medicine, medical devices, as well as replacement components and associated training services under the exceptional sanctions authorizations and restrictions provided in 31 CFR § 560.530. Additionally, transfer money transfers from certain countries to non-governmental organizations licensed by OFAC are permitted. The process of obtaining a license is highly complex and requires detailed justification and strict compliance with the established objectives. A license application must include comprehensive information about the purpose of the transfer, sources of funds, and provide a rationale that the transaction aligns with ofac regulations objectives (31 CFR § 501.801). If OFAC determines that the information provided is insufficient or does not meet the requirements, the application will be denied. In such a case, the entire process must be restarted, which can take months and require all parties involved’ significant time and resources.
An example of violations could involve a company attempting to send money to Iran under the guise of humanitarian aid but unable to prove that all funds will be used solely for medical purposes. In such a scenario, OFAC is likely to reject the recipient of the cash and license application, and the company and funds themselves may be frozen. Violating the rules established by 31 CFR § 560.516 will automatically result in the blocking of the transaction and the imposition of liability on the participants.
Moreover, even if you manage to obtain a specific license, you must be well aware and prepared for every step of your first account transfer to be closely monitored. Financial institutions and banks involved in the process are required to ensure compliance with all requirements, and be aware that any deviation from them will be immediately recorded and may result in further sanctions.
Compliance with OFAC sanctions
Compliance with the Iranian Transactions and Sanctions Regulations is not merely a formality; it is a critical requirement for anyone seeking to avoid serious legal consequences. 31 CFR Part 501 establishes stringent standards for all entities subject to sanctions imposed by U.S. jurisdiction. Violations of these standards can lead to significant fines and criminal prosecution. One of the most important aspects of sanctions compliance is having an effective compliance program in place. Such a program should include regular audits and checks for adherence to sanctions laws and requirements and the development of procedures for identifying and blocking suspicious transactions. Companies and banks are obligated to regularly audit their operations to ensure they comply with the requirements of 31 CFR Part 560. Any violations identified during such an audit can result in serious consequences.
What to do, if Funds are Returned
Imagine a scenario where your funds are returned, and you do not understand why. This can only mean one thing — something went wrong, and you need to take immediate action. 31 CFR § 560.211 requires that any assets associated with entities together with a sanctions violation be frozen. The reasons for the return transferring money can vary, but most often it is related to the absence of a license or errors in documentation. If you do not take action immediately, the risk is the situation will only worsen.
Your first step should be to consult with your bank or an attorney who understands the nuances of the Iranian Transactions and Sanctions Regulations. It is necessary to properly submit a license application, as regulated by 31 CFR § 501.801, or seek clarification from general license, for financial institutions. However, you and bank must be prepared for a complex process requiring precise justification that the transaction is legal and that any alleged violations were unintentional. Ignoring the issue will lead to even more severe consequences.
Sending Money to/from Iran: OFAC Rules, Licenses & Legal Requirements
Sending money to Iran is legally possible under specific OFAC general licenses — but navigating the rules requires precision. Under 31 CFR Part 560 (Iranian Transactions and Sanctions Regulations), U.S. persons may send personal remittances to family members in Iran without a specific license. Business transfers, payments to government entities, and transactions involving SDN-listed parties remain strictly prohibited. This guide explains exactly what is allowed, what is not, and when you need an OFAC license to proceed.
Quick Answer: Can You Legally Send Money to Iran?
Key Legal Options at a Glance
- Personal remittances to family — Permitted under OFAC General License (31 CFR § 560.550). No fixed dollar cap, but no commercial purpose allowed.
- Humanitarian transfers — Authorized for food, medicine, and personal medical expenses under separate GL provisions.
- Inherited funds and property proceeds — Permitted via GL when no SDN-listed parties are involved; must route through a third-country bank.
- Business payments, commercial transfers — Prohibited unless you hold an OFAC-specific license.
- All transfers — Must bypass SDN-listed individuals and entities, Iranian government bodies, and the Central Bank of Iran.
Legal vs. Illegal: Iran Money Transfers at a Glance
| Transaction Type | Legal Status | Authorization Required | Risk Level |
|---|---|---|---|
| Personal remittances to close family | ✅ Legal | General License (automatic) | Low if documented |
| Monetary gifts to individuals (non-commercial) | ✅ Legal | General License (automatic) | Low if documented |
| Humanitarian transfers (food, medicine) | ✅ Legal | General License (automatic) | Low |
| Inherited funds / property proceeds | ⚠️ Conditional | General License; no SDN parties | Medium — verify all parties |
| Property sold after immigrating to USA | ⚠️ Specific License | Specific OFAC license required | High without license |
| Business payments to Iranian companies | ❌ Prohibited | Specific license (rarely granted) | Very High |
| Payments to Iranian government entities | ❌ Prohibited | Not licensable in most cases | Critical |
| Payments to SDN-listed individuals | ❌ Prohibited | Not licensable | Critical — criminal exposure |
| Hawala / informal transfers without OFAC license | ❌ Prohibited | Specific license required | Very High — active enforcement |
| Cryptocurrency transfers to sanctioned entities | ❌ Prohibited | Not licensable | Very High — OFAC tracks blockchain |
Personal Remittances to Iran — What OFAC Allows
Under the Iran sanctions framework (31 CFR Part 560), OFAC has issued general licenses that automatically authorize personal remittances without requiring individual applications. These are among the few types of transfers that U.S. persons can legally make to Iran without a specific license. Here is what qualifies:
What Counts as a Personal Remittance
A personal remittance under OFAC rules is a non-commercial transfer of funds to a close family member in Iran intended for personal or household expenses. This includes:
- Monthly family support payments (living expenses, medical care, education)
- One-time monetary gifts for personal use
- Funds for family members’ travel outside Iran
- Inherited cash or funds from the sale of property acquired before the sender immigrated to the United States
- Proceeds from selling inherited property in Iran (where no SDN-listed party is involved)
What Is Not Covered by the General License
The general license for personal remittances does not cover:
- Any transfer that benefits the Iranian government, state-owned entities, or the Central Bank of Iran
- Transfers to individuals or entities on OFAC’s SDN list
- Charitable donations (these require a separate specific license)
- Business-related transfers, even to family members who operate businesses
- Payments for real estate purchased after the sender moved to the United States
The SDN Check: Non-Negotiable
Before any transfer — even a personal remittance — you must verify that no party involved (sender, recipient, intermediary bank) appears on OFAC’s Specially Designated Nationals (SDN) list. A single SDN-listed intermediary bank in the chain can make an otherwise-legal transfer illegal. Our attorneys conduct full SDN screening as part of any Iran transfer consultation. Learn more about SDN list removal if a party has been designated.
How Routing Works: Third-Country Banks
Direct transfers between U.S. banks and Iranian banks are prohibited. Even if your transfer is authorized under a general license, it must route through a bank in a third country — typically Turkey, UAE, or an EU country — that maintains correspondent banking relationships with Iran. U.S. financial institutions are prohibited from processing such transactions directly. This routing complexity is why even fully legal remittances often require legal guidance.
How to Get an OFAC License for Iran Transfers
When your transfer falls outside the automatic general license categories — commercial transactions, post-immigration property sales, large estate transfers, or any payment involving unique circumstances — you must apply for an OFAC-specific license (also called a “specific license” or “special license”). Here is how the process works:
Step 1: Determine Whether a Specific License Is Required
Start by checking whether your transaction is already covered by a general license under 31 CFR Part 560. Many personal remittances and humanitarian transfers do not require a separate application. However, if your transfer involves:
- Property purchased in Iran after immigrating to the United States
- Business transactions or commercial payments
- Movable property received as a gift in Iran
- Closing a bank account in Iran and transferring the balance
- Any transaction involving a blocked entity or unusual party structure
…you will need a specific license from OFAC.
Step 2: Prepare Your Application
OFAC specific license applications are submitted through the agency’s online portal (ofac.treasury.gov). A complete application includes:
- Full identification of all parties (sender, recipient, financial institutions)
- Detailed description of the transaction, purpose, and dollar amount
- Supporting documents (contracts, estate documents, property records, bank statements)
- Legal basis for why the transaction should be authorized
- Compliance certifications confirming no SDN involvement
Incomplete or poorly documented applications are routinely denied. An experienced OFAC licensing attorney significantly increases your approval rate by framing the application correctly and anticipating OFAC’s review criteria.
Step 3: OFAC Review Timeline
OFAC does not publish fixed processing times. Simple cases involving personal remittances or estate matters may be resolved in 4–8 weeks. Complex commercial transactions or cases involving parties with any SDN proximity can take several months. OFAC may request additional documentation (“supplemental information request”) during review, which extends the timeline.
Step 4: Compliance After Approval
An approved specific license is not a blank check. It authorizes a specific transaction under specified conditions. You must comply with all license terms, maintain records of the transaction for at least 5 years (OFAC record retention requirement), and report the transaction if required. Violating license conditions is itself an OFAC violation.
Which Services Can Send Money to Iran?
This is the most common practical question — and the answer is complicated. Major money transfer operators are generally not available for Iran transfers due to the broad U.S. sanctions framework.
Western Union, Wise, and Remitly
Western Union, Wise, and Remitly do not offer direct transfers to Iran from the United States. All three are U.S.-regulated entities and cannot process Iran transfers without an OFAC export service license under 31 CFR § 560.418. None of these companies currently hold such licenses for personal remittances to Iran. If you see third-party services claiming to facilitate transfers through these platforms to Iran, treat this as a significant compliance red flag.
Third-Country Intermediary Banks and Exchange Offices
The most common legal mechanism for personal remittances to Iran involves:
- Third-country exchange houses in Turkey, UAE, or EU countries that are authorized to receive USD and convert to Iranian rial (IRR) for delivery to recipients in Iran
- Iranian exchange offices abroad — some operate legally in countries with active banking ties to Iran, though vetting is critical
- Correspondent banking through non-U.S. financial institutions — a U.S. person sends funds to a non-U.S. bank account, which then routes to Iran via an authorized Iranian bank not on the SDN list
The key compliance requirement: no U.S. financial institution may directly process the Iran-side of the transaction. The routing must stay outside the U.S. financial system once funds exit the sender’s account.
Hawala and Informal Transfers
Hawala networks are widely used for Iran remittances, but their legal status is precarious. Under 31 CFR §§ 560.204 and 560.206, U.S. persons are prohibited from exporting financial services to Iran without OFAC authorization — and hawala operators who lack licenses are providing unauthorized financial services. While hawala may seem practical, it exposes U.S. senders to significant enforcement risk. OFAC has actively pursued enforcement actions against unlicensed informal value transfer operators. A specific OFAC license is required to use a hawala network for Iran transfers legally, and approvals are rare.
Cryptocurrency Transfers
Cryptocurrency is not a sanctions workaround. OFAC has explicitly stated that sanctions prohibitions apply equally to digital currency transactions. If you transfer crypto to a wallet controlled by a sanctioned Iranian entity or individual, you are in violation regardless of the payment method. OFAC actively monitors blockchain activity and has sanctioned crypto addresses tied to Iranian entities. Using crypto for Iran transfers without a specific OFAC license carries the same legal exposure as any other unauthorized transfer.
Penalties for Illegal Transfers to Iran
OFAC Iran sanctions violations carry severe consequences. Under IEEPA and ITSR:
- Civil penalties: Up to $377,700 per violation or twice the transaction value (whichever is greater)
- Criminal penalties: Up to 20 years imprisonment and $1,000,000 in fines per violation
- Corporate liability: Financial institutions that process unauthorized Iran transfers face penalties, license revocations, and reputational damage
- No intent requirement for civil violations: OFAC can impose civil penalties even for “good faith” transfers that technically violate the rules
OFAC issued 14 enforcement actions in 2025, with Iran-related cases consistently among the highest-value penalties. Voluntary self-disclosure of violations typically results in significantly reduced penalties — another reason to consult an attorney before and after any Iran transfer.
Need Help With an OFAC License for Iran?
Iran money transfer cases are among the most technically complex areas of OFAC practice. The difference between a legal remittance and an OFAC violation can come down to a single party’s SDN status, the routing bank used, or a missing document. Our OFAC licensing lawyers have handled Iran-related remittances, estate transfers, business wind-downs, and specific license applications across dozens of cases.
We can help you:
- Determine whether your transfer qualifies under an existing general license
- Conduct full SDN screening of all parties in the transaction chain
- Draft and submit an OFAC specific license application
- Respond to OFAC supplemental information requests
- Advise on compliant routing through third-country financial institutions
- Handle OFAC enforcement defense if a violation has already occurred
OFAC General Licenses for Iran: What Transactions Are Permitted
The U.S. Treasury’s Office of Foreign Assets Control (OFAC) maintains a set of general licenses under the Iranian Transactions and Sanctions Regulations (31 CFR Part 560) that authorize specific categories of money transfers to Iran without requiring individual license applications. Understanding which category your transaction falls into is the critical first step. The table below summarizes the currently active general license categories for Iran-related financial transfers as of 2025–2026.
| License Category | What’s Permitted | Key Conditions | License Type |
|---|---|---|---|
| Personal Remittances to Family | Sending money to close family members in Iran for personal/household expenses, living costs, medical care, and education | Non-commercial purpose only; no SDN-listed recipients; must route through non-U.S. financial institution; no fixed dollar cap | General License (automatic) — 31 CFR § 560.550 |
| Educational Fees & Student Support | Tuition payments, academic fees, books, and living expenses for Iranian students studying outside Iran; educational materials to Iran | Payments must be for personal academic use; no benefit to Iranian government or state institutions; no commercial resale | General License (automatic) — 31 CFR § 560.550 |
| Humanitarian Transfers | Food, medicine, medical devices, and personal medical expenses; donations to recognized NGOs operating in Iran | Items/funds must meet OFAC humanitarian definition; NGO must not be SDN-listed; no dual-use goods; separate GL covers donations to charities (GL 8A related) | General License (automatic) — ITSR Humanitarian Provisions |
| Family Support — Inherited & Estate Funds | Transfer of inherited cash or proceeds from sale of property acquired before U.S. immigration; closing inherited bank accounts in Iran | Property must have been acquired before sender’s U.S. immigration; no SDN-listed parties in transaction; court/estate documentation required | General License (conditional) — specific license may be required for complex estates |
| Monetary Gifts (Non-Commercial) | One-time monetary gifts to individuals in Iran for personal use (weddings, emergencies, personal support) | No commercial purpose; recipient must not be SDN-listed or connected to Iranian government; no business investment | General License (automatic) — 31 CFR § 560.550 |
| Blocked Funds / Iranian Financial Institutions | Certain transactions involving Iranian financial institutions blocked under Executive Order 13902 (Iran General License L) | Narrow scope; applies to specific authorized financial institutions only; legal counsel strongly advised | Iran General License L (issued Oct. 2020) |
| Post-Immigration Property Sales | Proceeds from selling property in Iran acquired after the sender immigrated to the U.S. | Specific OFAC license required — not covered by general license; application must document full transaction history | Specific License Required |
| Business & Commercial Payments | Not permitted under any general license; requires specific OFAC license (rarely granted) | Prohibited for virtually all U.S. persons and companies; specific license process can take 6+ months | Specific License Required (rarely approved) |
Important: Even transactions covered by a general license may be blocked if any party in the transfer chain — sender, recipient, intermediary bank, or exchange house — appears on OFAC’s Specially Designated Nationals (SDN) list. Always conduct full SDN screening before proceeding. Our OFAC licensing attorneys provide SDN screening as part of every consultation.
Iran Money Transfer: Frequently Asked Questions
The following questions are among the most common we receive from individuals and families navigating Iran money transfer rules. Each answer reflects current OFAC regulations under 31 CFR Part 560 as of 2025–2026.
Can I send money to my family in Iran?
Yes — personal remittances to close family members in Iran are permitted under OFAC General License (31 CFR § 560.550) without requiring a separate application. You may send funds for living expenses, medical care, and education. The transfer must be non-commercial, must not benefit SDN-listed individuals, and must route through a third-country bank (not directly through U.S. financial institutions).
Which banks process Iran money transfers legally?
No major U.S. bank can directly process transfers to Iran — U.S. financial institutions are prohibited from serving as the direct conduit for Iran-side transactions. Legal transfers typically route through banks in Turkey, the UAE, Germany, or other countries that maintain correspondent banking relationships with Iranian banks not on the SDN list. Non-U.S. banks such as certain Turkish and UAE institutions may facilitate the Iran leg of the transfer, but you must verify their SDN status. Using an OFAC-experienced attorney to identify compliant routing is strongly recommended.
What is the maximum amount I can send to Iran?
There is no fixed dollar cap for personal remittances under the OFAC general license (31 CFR § 560.550). However, larger transfers attract greater scrutiny. The transfer must be for personal/household purposes — not investment, business, or commercial use. Transfers above certain thresholds may trigger Bank Secrecy Act (BSA) reporting requirements (e.g., Currency Transaction Reports for amounts over $10,000). For large remittances, we strongly advise obtaining a legal opinion confirming compliance before proceeding.
Can I send money to Iran for educational fees?
Yes — educational fees and student support payments fall within the personal remittances general license under 31 CFR § 560.550. This covers tuition payments, academic fees, books, and living expenses for Iranian students. The key condition is that the payment must be for personal academic use — not to Iranian state educational institutions (which may be SDN-linked). Payments to private universities or educational institutions outside Iran on behalf of Iranian students are generally permissible.
Is Western Union available for sending money to Iran?
No — Western Union, Wise, Remitly, and most major money transfer operators do not offer direct transfers to Iran from the U.S. These companies are U.S.-regulated entities and cannot process Iran-side transactions without an OFAC export service license (31 CFR § 560.418), which none currently hold for personal remittances. Transfers must instead route through authorized third-country exchange houses or correspondent banking channels. Be cautious of services claiming to offer Western Union or Wise-based Iran transfers — these are compliance red flags.
Do I need an OFAC license to send humanitarian aid to Iran?
Not always — many humanitarian transfers are covered under existing general licenses. Food, medicine, medical devices, and personal medical expenses are authorized under ITSR humanitarian provisions without a specific license application. However, charitable donations to organizations operating in Iran require a specific license, as does any transfer that benefits an Iranian government entity or SDN-listed organization. If you are sending funds through an NGO or charity, confirm their licensing status before transferring.
What happens if I accidentally send money illegally to Iran?
Even accidental or good-faith violations of Iran sanctions can result in civil penalties of up to $377,700 per violation (or twice the transaction value) (or twice the transaction value). OFAC does not require intent for civil violations. If you have already made a transfer that may violate sanctions, the most important immediate step is voluntary self-disclosure — which typically results in significantly reduced penalties. Contact an OFAC attorney immediately to assess your exposure and prepare a disclosure if needed.
Wire Transfers to Iran: What Is Permitted vs. Prohibited
| Transfer Type | Status | Conditions |
|---|---|---|
| Family remittances (personal) | Permitted (general license) | To non-SDN family members; personal use only |
| Humanitarian payments (food, medicine) | Permitted (general license) | Not to Iranian government; authorized recipients only |
| Legal services fees | Permitted (general license) | Payment for legal representation in U.S. proceedings |
| Dollar-denominated commercial transfers | Prohibited | Blocked by U.S. correspondent banks |
| Transfers to Iranian government entities | Prohibited | Includes Central Bank of Iran |
| Transfers to SDN-listed individuals/entities | Prohibited | Full asset block applies |
| OFAC-licensed specific transactions | Permitted with licence | Requires prior OFAC specific licence application |
Conducting business in a global economy often has risk and requires flexibility and the ability to quickly adapt to changing conditions. However, when it comes to financial transactions involving Iran, caution is paramount. The Iran sanctions regime established by the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) leaves no room for error. Any deviation from established norms can lead to severe consequences, including asset freezes and criminal prosecution. The detailed regulations set forth in sanctions programs 31 CFR Part 560 (Iranian Transactions and Sanctions Regulations, ITSR) are the key aspect of conducting any transactions involving Iran. If you are planning to wire transfer from Iran to the United States or other countries or vice versa, this process will require not only knowledge but also legal support at every stage of underlying transaction.
Wiring funds from Iran to the U.S
The first question anyone planning to wire funds from the country of Iran to the United States asks is: what is permitted, and what is not? The answer to this question lies in 31 CFR § 560.550. According to this provision, non-commercial, personal remittances between the U.S. and Iran (such as family support) are permitted, provided they comply with strict requirements. Transfers transferring money from iran to may only be conducted through registered U.S. depository institutions, exchange or securities broker-dealers.
The primary objective is to prevent situations where funds originating from Iran could be used to finance prohibited activities or organizations. For this reason, all transactions must be processed through verified countries and registered financial institutions. Attempts to bypass this system by using informal or shadow channels of exchange, such as Hawala, will immediately result in sanctions. In such cases, the other government or financial institution may block the transfer, and OFAC may initiate an investigation, which could lead to asset freezes and substantial fines.
Additionally, it is crucial for banks to remember that 31 CFR § 501.603 requires all financial institutions to immediately notify OFAC of any suspicious transactions. This provision underscores the necessity of strict adherence to all established procedures, as any violation will be treated as an attempt to circumvent the sanctions regime. If a bank determines that a customer’ transaction violates the sanctions, the bank and customer’ funds may be frozen, and recovering them may be extremely difficult, if not impossible.
ARE YOU PLANNING TO TRANSFER FUNDS FROM IRAN TO THE UNITED STATES OR ANOTHER COUNTRY? SEEK COUNSEL FROM SANCTIONS ATTORNEYS.
Is it possible to wire money to Iran?
Transferring funds to Iran is a domain under particular scrutiny by U.S. regulators. According to 31 CFR § 560.516, all fund transfers to Iran are prohibited unless licensed by OFAC. Section 560.516 also allows for certain transactions but prohibits direct debiting or crediting of money laundering Iranian bank accounts. The rules concerning personal non-commercial money transfers as outlined earlier in 31 CFR § 560.550 are also applicable.
Exceptions for fund transfers to Iran do exist, but they primarily pertain to humanitarian purposes or payment for medical services, and even then, only after obtaining a Special License from OFAC. This includes transfers related to the commercial sale, export, re-export, and accompanying provision of services and software for agricultural products, medicine, medical devices, as well as replacement components and associated training services under the exceptional sanctions authorizations and restrictions provided in 31 CFR § 560.530. Additionally, transfer money transfers from certain countries to non-governmental organizations licensed by OFAC are permitted. The process of obtaining a license is highly complex and requires detailed justification and strict compliance with the established objectives. A license application must include comprehensive information about the purpose of the transfer, sources of funds, and provide a rationale that the transaction aligns with ofac regulations objectives (31 CFR § 501.801). If OFAC determines that the information provided is insufficient or does not meet the requirements, the application will be denied. In such a case, the entire process must be restarted, which can take months and require all parties involved’ significant time and resources.
An example of violations could involve a company attempting to send money to Iran under the guise of humanitarian aid but unable to prove that all funds will be used solely for medical purposes. In such a scenario, OFAC is likely to reject the recipient of the cash and license application, and the company and funds themselves may be frozen. Violating the rules established by 31 CFR § 560.516 will automatically result in the blocking of the transaction and the imposition of liability on the participants.
Moreover, even if you manage to obtain a specific license, you must be well aware and prepared for every step of your first account transfer to be closely monitored. Financial institutions and banks involved in the process are required to ensure compliance with all requirements, and be aware that any deviation from them will be immediately recorded and may result in further sanctions.
Compliance with OFAC sanctions
Compliance with the Iranian Transactions and Sanctions Regulations is not merely a formality; it is a critical requirement for anyone seeking to avoid serious legal consequences. 31 CFR Part 501 establishes stringent standards for all entities subject to sanctions imposed by U.S. jurisdiction. Violations of these standards can lead to significant fines and criminal prosecution. One of the most important aspects of sanctions compliance is having an effective compliance program in place. Such a program should include regular audits and checks for adherence to sanctions laws and requirements and the development of procedures for identifying and blocking suspicious transactions. Companies and banks are obligated to regularly audit their operations to ensure they comply with the requirements of 31 CFR Part 560. Any violations identified during such an audit can result in serious consequences.
What to do, if Funds are Returned
Imagine a scenario where your funds are returned, and you do not understand why. This can only mean one thing — something went wrong, and you need to take immediate action. 31 CFR § 560.211 requires that any assets associated with entities together with a sanctions violation be frozen. The reasons for the return transferring money can vary, but most often it is related to the absence of a license or errors in documentation. If you do not take action immediately, the risk is the situation will only worsen.
Your first step should be to consult with your bank or an attorney who understands the nuances of the Iranian Transactions and Sanctions Regulations. It is necessary to properly submit a license application, as regulated by 31 CFR § 501.801, or seek clarification from general license, for financial institutions. However, you and bank must be prepared for a complex process requiring precise justification that the transaction is legal and that any alleged violations were unintentional. Ignoring the issue will lead to even more severe consequences.
Message a sanctions lawyer on WhatsApp — confidential, reply within 24 hours.
Frequently Asked Questions: Sending Money to/from Iran
Is it legal to send money to Iran from the USA?
It depends on the purpose. OFAC’s General License D-2 permits personal remittances to family members in Iran. However, payments to the Iranian government, SDN-listed individuals, or for commercial purposes remain illegal. The rules are complex — consulting an OFAC lawyer before making transfers is strongly advised.
How much money can I send to Iran legally?
OFAC does not set a specific dollar cap on personal remittances under General License D-2, but transfers must be genuinely personal and cannot benefit the Iranian government or SDN-listed parties. Banks have their own compliance thresholds and may refuse even technically legal transfers.
Which money transfer services work for Iran?
Very few mainstream services support Iran transfers due to sanctions compliance risk. Western Union, Wise, Remitly, and PayPal do not support Iran. Some specialized regional remittance services operate in this space, but any service used must itself comply with OFAC regulations.
What is an OFAC specific license for Iran transfers?
If a transfer does not qualify under a general license, you can apply to OFAC for a specific license — a formal authorization for a particular transaction. Processing takes 1–6 months. An OFAC lawyer can significantly improve your application’s success rate and ensure proper documentation.
What are the penalties for illegally sending money to Iran?
Under IEEPA, civil penalties reach up to $377,700 per violation (the statutory maximum is adjusted for inflation) or twice the transaction value, whichever is greater. Willful violations are criminal offenses punishable by a fine of up to $1,000,000, up to 20 years in prison, or both. OFAC enforcement is active — multiple Iran sanctions enforcement actions occur each year. Voluntary self-disclosure significantly reduces penalties.